All Categories
Featured

Comparing Term and Whole Life Insurance Comparison
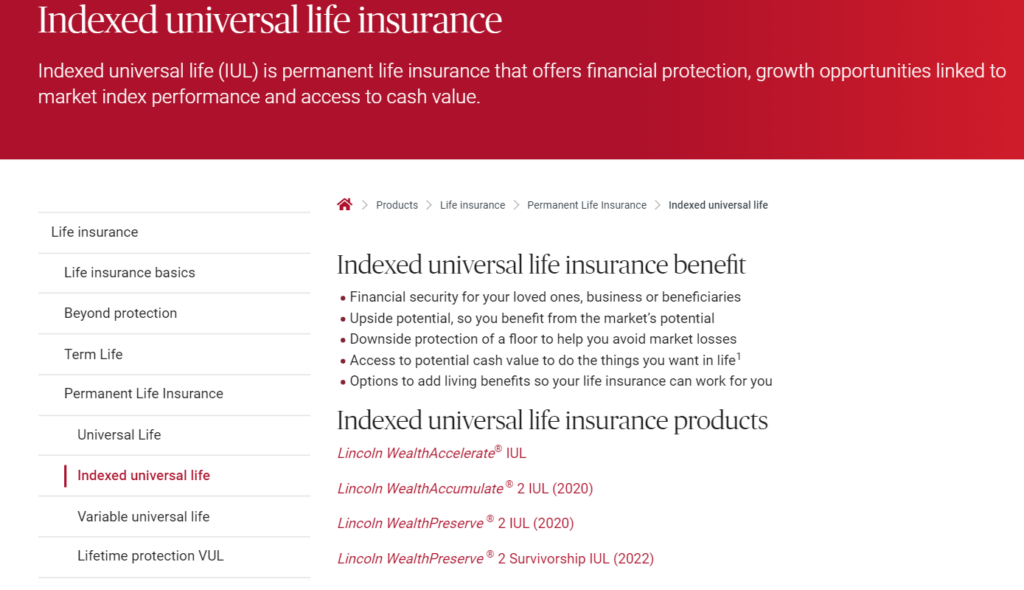
These same Indexed Universal Life products will considerably underperform if they're light financed and/or their efficiency does not have. That means that the internal charge load baked into the product is higher than it must be, and greatly depending on efficiency to outrun the costs. These improperly developed items that get offered to the unwary masses are the factor you frequently hear IUL is an ongoing combination of debits and credits, so it's sensible to understand what both sides of the journal appear like.
Insurance in Oxnard CAIt's pretty standard nowadays for the majority of IUL policies to have some sort of taking part loan alternative, where your money value still has market direct exposure even while borrowing versus it for emergencies or chances. It's sensible to consider the spread in between whatever the loan rate is and the cap so you understand what kind of positive arbitrage you can expect in bullish years.
Having a built-in system to catch this prospective arbitrage will be critical in choosing the best-performing IUL policy. There are IUL calculators to assist you identify if you can expect long-lasting favorable arbitrage on your cash value over various timeframes during bull and bear markets. Exact same age, same rating, Same premiumDifferent business, Various designs, Significantly various cash valuesSee how your policy stacks up.
For these factors,, who is remaining abreast of this quickly changing market and can inform you to the most recent news and opportunities. It's not surprising that Penn Mutual ranks the greatest of the very best IUL companies in regards to warranties considering that they also use the best-performing Whole Life policy, a product understood for its warranties.
Numerous of Penn Mutual's indexed accounts included an ensured 1% floor, which implies that even in down market years, you make interest to offset the continuous expense of the death benefit. In spite of this 1% flooring, Penn Mutual still offers competitive caps on its S&P 500 strategies. Unlike the other finest IUL business on this list, Penn Mutual does NOT use Volatility Control Index methods.
Comparing Medicare Advantage Plans
(In case you missed it above, VCIs are algorithmic market timing strategies handled by well-known financial investment banks with high internal costs and a lack of openness). Competitive Caps on the S&P 500 (often with a 1% floor instead of 0%)The ability to raise your S&P 500 cap (for an extra fee or spread of around 3%)Uncapped S&P 500 crediting methods for maximum growthWith Penn Mutual's contractually locked 6% policy loan rate for the life of its IUL policy, you can keep your cash worth operating in the S&P 500 Index even while borrowing against it for emergency situations or outside financial investment chances.
Allianz occurs to be the only on the list and a foreign stock company at that. It's legitimate to fret that a German parent company may not have allegiance to American policyholders if financial times get tough, but others like the fact a foreign stock company has varied sources of incomes in varied insurance coverage markets.
Insurance in Oxnard CAThis allows them to use their "rate lock feature," where IUL policy owners can freeze whatever gains they have at any point throughout the year. Nevertheless, it's worth noting that you can only do this with their different volatility control indexes (VCIs) and not the pure S&P methods. In fact, Allianz likewise has different cost choices that allow you to increase your direct exposure to their indexed choices.
Allianz is among the best IUL business since of their diverse set of IUL investment optionsIt's worth keeping in mind that I have actually been an Allianz policyholder because 2014, and I can vouch for the fact that my IUL caps and involvement rates aren't as competitive as what they have actually regularly offered on whatever their newest product is.
Burial Insurance Benefits
Therefore, it's important to stress-test how Allianz's IUL policy holds up at lower crediting rates compared to the other top Indexed Universal Life companies. A broad variety of unique indexes to choose fromRate-lock feature when utilizing the volatility control indexesAbility to be more aggressive with a 40% multiplier (for a 1% fee)Locked 5% loan rate to borrow against any of the indexed accountsTheir "Index Lock" only deals with Volatility Control Indexes, not the pure S&P methods.
Ok, there, I did it. You know you were thinking it too. However that actually is why Nationwide is one of the leading IUL business. Their size, score, and overall monetary strength are unmatched. Not only that, but they are a true shared business, implying they have no outside investors nor a holding company to siphon earnings to.

Latest Posts
Understanding How Whole Life Insurance Works

Securing Burial Insurance to Support Families
Selecting Medicare Advantage Plans